 oky-pratista
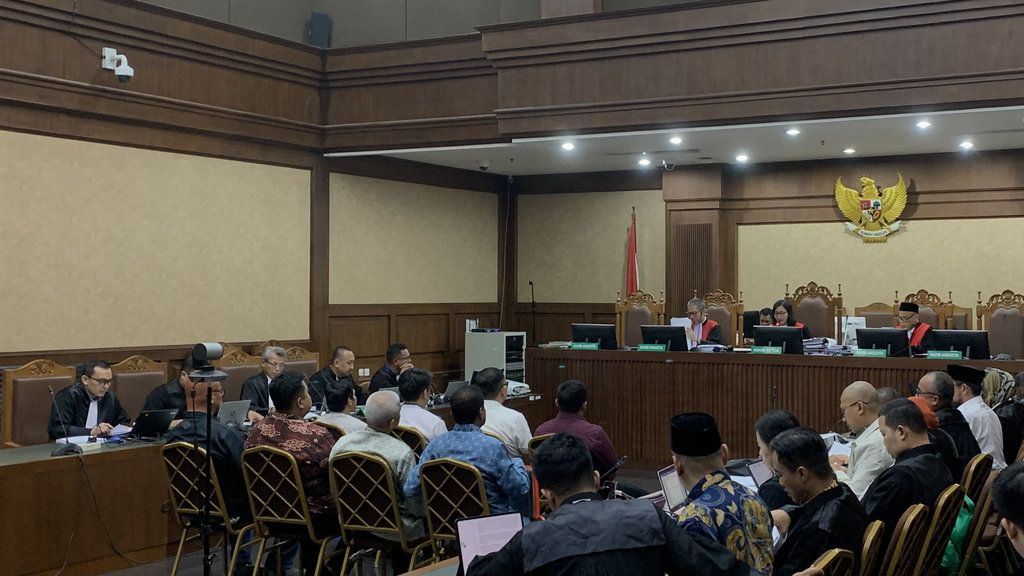
一家 squarely in the middle of a court session, a prosecutor's witness testified that there exists a practice whereby PIHK distributes religious holiday allowance funds, commonly known as THR, to an official within the Ministry of Religious Affairs. The testimony, delivered by a person identified as Al Fatih, places the alleged practice inside a criminal case that has already attracted sustained judicial scrutiny. What the witness conveyed is not a general accusation but a specific account of recurring conduct, and the distinction matters because allegations of systemic practice carry heavier evidentiary demands than isolated claims.
The phrase that anchors the testimony is tradisi. In courtroom usage, that term implies repetition over time rather than a single transaction. A witness who describes a one-time handover speaks of an event; a witness who describes recurring handover patterns speaks of a practice. The second category, by its nature, cannot be established through testimony alone and normally requires documentary corroboration, such as corporate ledger entries, approval memos, transfer records, or the written minutes of board meetings. Whether such supporting records have been presented in this proceeding remains outside the information currently available.
Isu Pokok: Apa Itu THR dan Siapa Penerimanya
THR is a statutory entitlement under labour regulation, including Minister of Manpower Regulation Number 6 of 2016, and is owed by employers to workers who meet the conditions attached to the holiday. The category of recipient therefore depends on employment status. Officials of the Ministry of Religious Affairs are public apparatus rather than employees of a private or state-owned enterprise, so a payment to them would not sit naturally within the ordinary framework of the labour regulation governing THR entitlements. That legal gap is precisely what raises the significance of the witness account.
When a corporate entity transfers funds to a public official who holds no claim to such entitlement, the issue ceases to be one of labour compliance. It becomes a question of whether state funds were disbursed improperly, and whether any quid pro quo attached to the transfer.
Klaim yang Diucapkan dan Fakta yang Tersedia
Klaim: ada tradisi THR dari PIHK kepada pejabat Kemenag, serta pengakuan bahwa dana CertainProvided Kier distributes to otherReligious officials.
The available material confirms only that such statements were uttered in a judicial setting. It does not confirm their content, completeness, or accuracy. A single witness account constitutes an evidentiary foundation, not a proven fact. The witness admitted that the distribution extended to other Ministry officials, which if accurate would widen the alleged scope beyond a single recipient. However, the same admission raises a methodological question that the court must resolve: how the witness obtained knowledge of what occurred in transactions involving other named individuals, and whether that knowledge rests on direct observation, hearsay, or inference.
Mengapa Tuduhan Ini Ber sensitivitas Tinggi
Allegations touching public officials fall within a legal environment where proof requirements are deliberately stringent. Under the principal provisions governing criminal acts against state organs, and the anti-corruption statute as amended, an element of intent is decisive. A transfer of corporate funds must be shown to have been made with the purpose of influencing an official act, or to have constituted an improper use of assets. Absent proof of purpose, an argument can remain that the payments were characterised internally as budget allocations, corporate social contributions, or appreciation tokens rather than instruments of influence.
That alternative framing is not established. It is, however, the type of defence that typically emerges, and its plausibility underscores why the prosecution would need more than testimony to secure a conviction on this particular point.
Bagian yang Belum Terverifikasi
Several elements remain open. First, the full transcript of the hearing is required, since a written record permits assessment of whether the statement was made clearly, whether leading questions were put, and whether counsel challenged it. Second, it is unconfirmed whether financial records have been entered as evidence. Third, the response of the defence and of any implicated party is not reflected in the material at hand. Fourth, the status of the case, whether at indictment, trial, or evidentiary stage, has not been specified, and that status determines how much weight the account currently carries.
Catatan Verifikasi dan Kesimpulan
Berdasarkan verifikasi terhadap informasi yang tersedia, klaim mengenai tradisi THR dari PIHK kepada pejabat Kemenag dapat dicatat sebagai testimoni yang belum terkonfirmasi secara independen. Data menunjukkan satu sumbersidang, namely keterangan seorang saksi dalam persidangan, dan sumber tunggal tidak memadai untuk确立 establish fakta. Fakta yang dapat dinyatakan secara aman adalah bahwa pernyataan ituCCSCCS diucapkan di persTMSean dan bahwa》所涉 isinya menyangkut dugaan Hibah distribute dana kepada ][ officials yang secara normatif tidak ber entitled atas THR. Everything beyond that point requires documentary verification.











Comments (0)