 oky-pratista
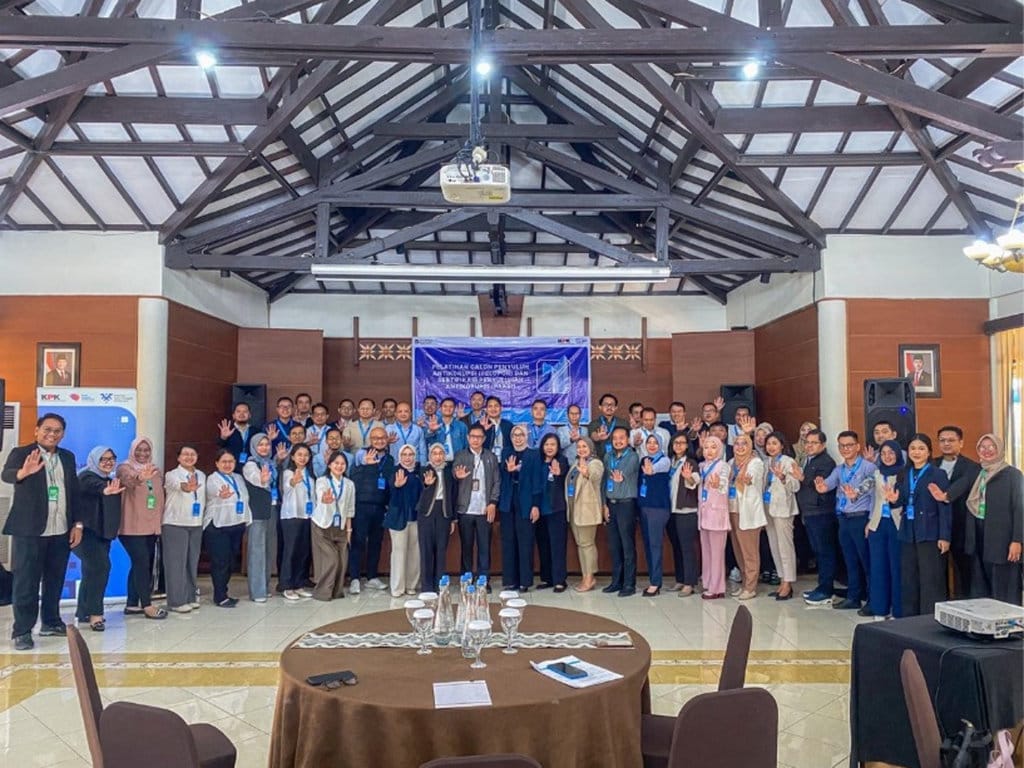
Badan Pemeriksa Keuangan dan Bank Rakyat Indonesia tercatat|Luara program's integrity agenda through a collaboration that, according to available descriptions, centers on PELOPOR BRI 2026. The program is positioned as an internal movement aimed at embedding anti-corruption values among employees, rather than a punitive campaign directed at external parties.
The framing matters. Anti-corruption programs announced by financial institutions often combine two approaches: enforcement against misconduct, and prevention through values education. The second approach is the one emphasized in the available material. Nothing in the description indicates sanctions, investigations, or legal action; the language used concerns culture, integrity, governance, and the formation of change agents within the workplace.
Empat Pilar yang Disebutkan
The program narrative rests on four stated components: integrity, good governance, anti-corruption culture, and the creation of agents of change inside the organization. Each of these terms carries different operational meaning, and only some are typically accompanied by measurable indicators such as training hours, certification counts, or reporting rates.
Integrity in this context refers to adherence to internal codes of conduct and ethical standards. Governance refers to the structural side — how decisions are made, documented, and audited. Culture refers to the informal layer: what employees consider acceptable when no supervisor is watching. The fourth pillar, change agents, describes individuals expected to model the desired behavior and influence peers.
Mengapa Kolaborasi différemment dengan conventionally
A collaboration between a state audit institution and a commercial bank is unusual enough to warrant scrutiny. State institutions typically hold oversight functions over public funds, while private banks operate under prudential supervision by the financial services authority. A joint program between them is not a routine arrangement.
That unusual character is precisely why the distinction between oversight and partnership needs to be made clear. Oversight implies inspection and finding of irregularities. Partnership implies joint design of an initiative. The available description uses the second framing. Whether this partnership constitutes an independent assessment or an internal facilitation exercise is not specified in the material reviewed.
Yang Tersedia dan Yang Tidak
A fair reading of the available information requires stating plainly what it contains and what it does not.
It does contain: the identities of the two institutions involved, the name of the program, and the four thematic areas the program intends to address. It does not contain: a launch date, a program duration, the number of participating employees, the selection mechanism for change agents, an evaluation metric, a budget figure, or any named official responsible for implementation.
These omissions are not unusual for a short institutional announcement, but they do limit verification. Without a baseline — how many employees were reached, what the measured compliance indicators were before the program, what changed after — claims of strengthened culture remain assertions of intent rather than demonstrated outcomes.
Catatan bagi Pembaca
Program announcements of this type describe what an institution intends to do. That is a legitimate object of reporting. It is not, on its own, evidence that the intended outcome occurred. The distinction between an announced commitment and a verified result is the line that separates descriptive reporting from promotional content.
Readers seeking to assess the program's actual impact would need subsequent materials: implementation reports, participant counts, evaluation findings, or third-party assessment. Until such data appears, the appropriate characterization is that a collaborative initiative has been declared, with its stated objectives documented and its results not yet demonstrated.









Comments (0)