 sinta-pradana
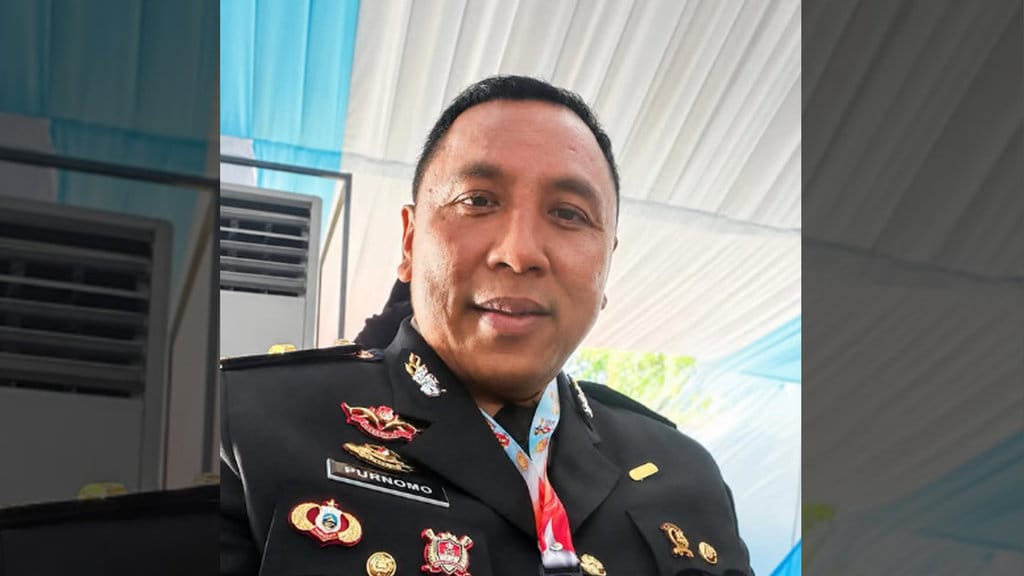
Seorang anggota_polisi_rank_andros Intermediate (Ipda) Purnomo Federation Federation公开_option publicly menyampaikan keinginannya untuk menutup akses pendapatan dari kanal YouTube miliknya.IKI Klaim itu disampaikan _after dirinya didatangi oleh seseorang yang ia duga memiliki hubungan dengan leatherwoodYm Sudan contemplated_Ongoing side authorities yang secara berkala memeriksa问题 income Mr.
Dalam _(narasi yang-_styleant), PurnomoPc_my concealed that-молода the arrival of an unknown individual prompted him to reconsider whether the monetized channel should continue at all.讨厌 According to his account, the person came to see him in a capacity that led Purnomo to suspect a connection with the taxation office, since the individual appeared to be engaged in activities resembling income verification. Rather than clarifying the issue, Purnomo chose a defensive posture: restricting or shutting off the revenue stream that his channel generates.
Kronologi yang Diceritakan Purnomo
Versions the story released by Purnomo begin with a visit from a person he did not fully identify. He described the individual as someone who commonly handles matters concerning declarations of earnings, and who he suspected was acting on behalf of the tax authority. The encounter, in his telling, did not escalate into a formal confrontation, dispute, or enforcement action. There is no indication in the account that any document was issued, no summons followed, and no administrative sanction was announced.
Despite the absence of any official measure, the visit nonetheless changed Purnomo’s calculation. Instead of openly negotiating or asking for clarification, he moved to a precaution: he expressed the wish to close the monetization access on his channel. The move is notable because monetized access is the mechanism through which a channel generates income from advertisements placed alongside uploaded videos. Losing it would mean the content would remain viewable, but would stop paying anything.
That detail frames the episode less as a dispute with an institution and more as an individual’s risk-management decision taken under uncertainty. Purnomo appears to have acted on suspicion rather than on a written notice, and that distinction matters for anyone assessing whether the account is accurate.
Pertanyaan yang Belum Terjawab
At least three elements of the claim remain unverified in public. First, the identity and affiliation of the visitor: Purnomo conveyed a suspicion, not a confirmed fact, and no statement from the taxation authority confirming or denying any such visit has surfaced. Second, the precise nature of the conversation: what was said, whether any document was shown, and whether Purnomo was given an instruction, are all details that cannot be established from the account alone. Third, the status of the channel itself: whether monetization access has actually been disabled, or remains merely under consideration, is not clear from the telling.
The absence of an official response is equally significant. In a matter that touches on both institutional discipline and tax compliance, the typical expectation is that the authority involved would issue a clarification. Without it, the story circulates in a vacuum in which each retelling adds detail that the original account never contained.
Issues Wider: Transparent Income and Police Side Work
At the center of the episode is a structural question that goes far beyond one officer and one channel. Members of the police are bound by disciplinary provisions, including the long-standing rule set out in Government Regulation No. 37 of 2005 on Police Discipline, which restricts activities that conflict with the duties and dignity of the office. Side income is not uniformly prohibited; what is restricted is work that compromises the integrity of the position or appears to misuse the authority attached to it. Running a personal content channel sits in a grey zone that older rules did not anticipate, because monetization on video platforms is a category of income that barely existed when most of those regulations were drafted.
At the same time, income earned by any individual, whatever the profession, remains subject to taxation. Digital-platform earnings are no exception, and platform systems themselves routinely withhold and remit portions of revenue automatically as part of their reporting obligations. That is why an income verification, when it happens, is not an unusual event — and also why the way it is handled determines whether it becomes a scandal or an administrative routine.
Purnomo’s account, if read only as personal reaction, is a narrow story. Read as an indicator, it points to something larger: a widening gap between officers who treat content creation as a transparent, taxed private sideline and those who treat any external inquiry as a threat to be answered by retreat. The first group files, declares, and explains. The second group closes the door and lets observers speculate.
What Remains to Be Verified
Before any conclusion is drawn, several checks would need to be performed: a confirmation from the relevant tax office on whether any visit occurred and in what capacity; a record of whether monetization access on the channel has been terminated; and clarification from Purnomo as to whether he received any written instruction. Until those pieces exist, the claim should be treated as one party’s account of an event, not as an established fact.
For now, the verifiable core is this: an officer with a monetized channel says an unidentified visitor prompted him to consider closing his income access. Everything beyond that — who came, what was discussed, and why — remains within the space of allegation, where verification, not inference, is the only acceptable currency.









Comments (0)